Categories
Abilene, TXPublished October 2, 2026
What Buyers and Sellers Should Know About Mortgage Rates in Abilene, TX in 2026
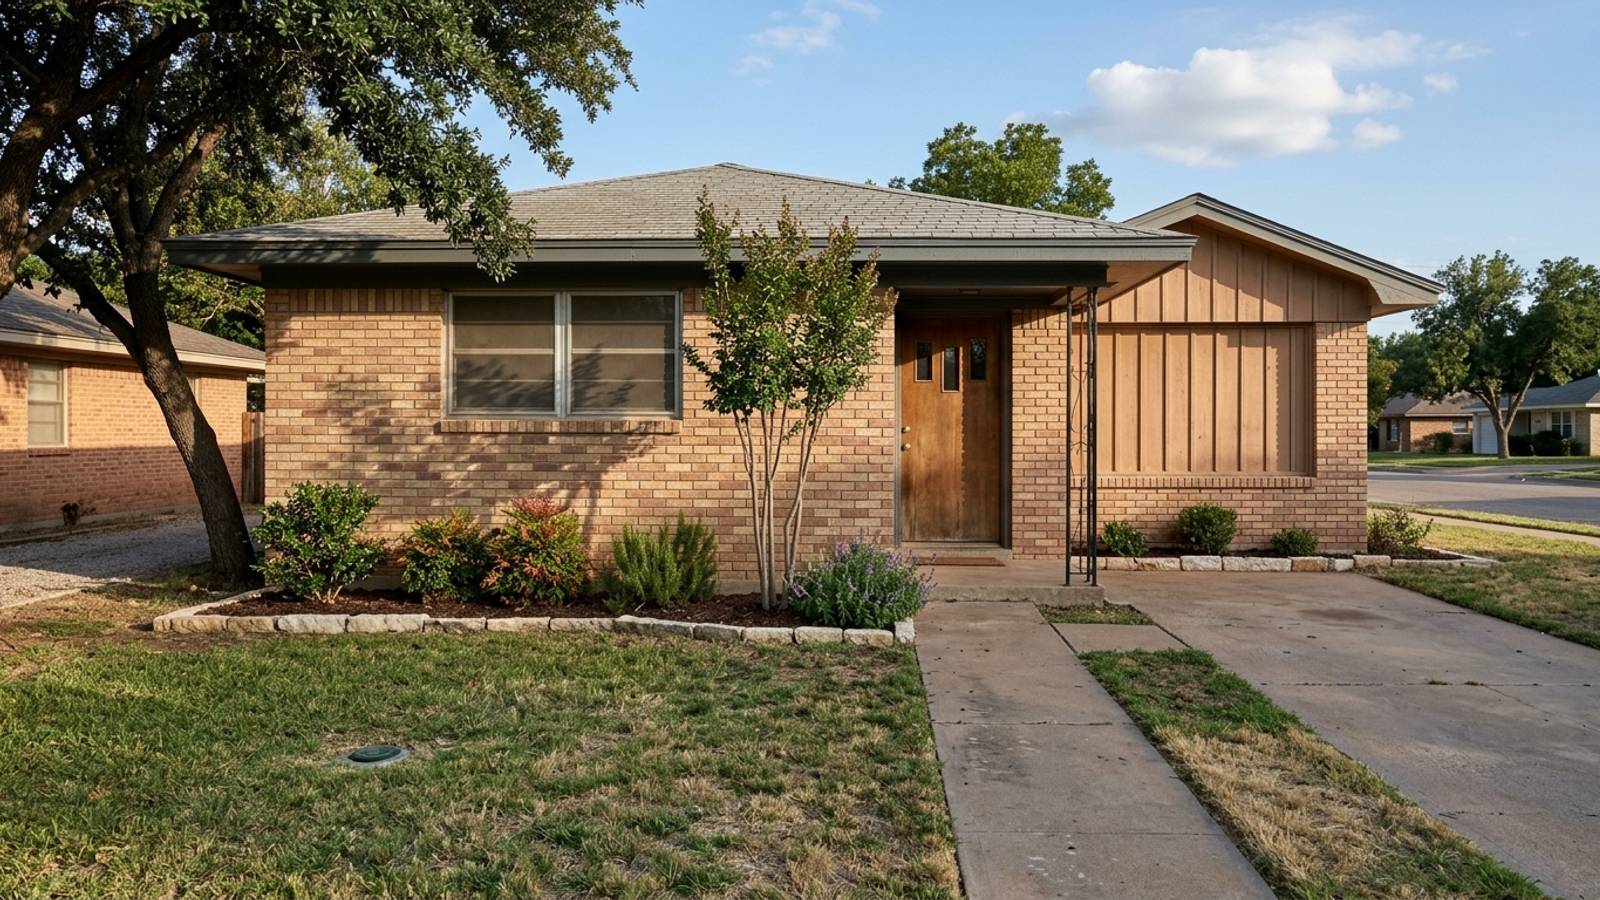
Homes in Abilene are spending roughly 20 days on the market before going under contract. With a median sale price around $292,000, a shift in financing costs hits both sides of the table - first-time home buyers in Abilene watching their monthly payment ceiling, sellers watching their buyer pool.
These cost mechanics let you build a real budget or price a listing with confidence. Chasing national headlines won't get you there. What matters is how these financial moves land in Taylor County specifically.
How Daily Mortgage Rates Work in Abilene
A mortgage rate is simply the cost you pay to borrow money for a home purchase. Inflation data, bond market activity, and federal monetary policy all push that number around - and they move constantly.
That's why the cost to borrow can shift multiple times in a single day. Lenders price their loans against the broader bond market, which means the quote you see Tuesday morning may look different by Thursday afternoon. That's not a sales tactic. That's just how it works.
Where to Find Your Actual Rate
National news broadcasts and public rate websites aren't going to tell you what you'll pay. Those numbers are averages built around ideal borrower profiles who are also paying extra upfront fees - not your situation.
What you need is a personalized quote or a Loan Estimate from a lender. That document accounts for your credit profile, the specific Abilene property you're buying, and the loan program that fits your circumstances.
Why Rates Move From Day to Day
Most home loans don't stay with the lender who writes them. Lenders sell them to investors on the secondary market, and those investors set the terms. When inflation runs high, investors demand higher yields - your borrowing cost goes up. When economic growth slows or inflation cools, that pressure eases and costs often drop.
That daily tug-of-war is the baseline every lender uses to build your quote.
What a Rate Change Means for Your Buying Power
Buyers spend a lot of energy focused on the sticker price of a house. The financing cost is what determines what leaves your bank account every month. Even a half-percent shift changes both your payment and your total budget.
When borrowing costs rise, your maximum purchase price falls if you're trying to hold a payment steady. When they dip, you get room to stretch your offer or simply keep more cash each month.
Running the Numbers on an Abilene Home
Take a home near the local median price of roughly $292,000 with a 20% down payment. On a 30-year fixed loan at 6%, the principal and interest payment runs about $1,400 per month. At 7%, that same loan costs around $1,550 per month.
That's before local taxes. A typical composite property tax rate in Abilene runs roughly 2.0% to 2.3% of assessed value, which adds several hundred dollars to your total monthly obligation. The payment you're budgeting for is higher than the principal-and-interest number alone.
Balancing the Purchase Price and the Rate
Waiting for a cheaper borrowing environment can backfire if local values rise while you're sitting on the sidelines. Abilene homes are currently selling for about 99.3% of their list price - that's strong local demand. Whether today's prices or potentially different financing terms down the road make more sense for your situation is a calculation worth doing before you decide to wait.
Fixed vs. Adjustable-Rate Mortgages and Loan Types
The type of loan you choose directly changes the borrowing cost a lender offers you. Lenders price for risk, and different loan structures carry different levels of predictability for the investor buying that loan downstream.
Government-backed loans often carry lower baseline pricing than conventional loans, but they come with different upfront funding fees and mortgage insurance rules. Your lender can walk you through the comparison based on your actual financial picture.
Comparing 30-Year and 15-Year Fixed Loans
A 30-year fixed loan spreads your balance over three decades, keeping the monthly payment as low as possible. Because the lender waits longer to get their money back, the financing cost is typically higher than on shorter-term options.
A 15-year fixed loan compresses that schedule - the monthly payment is much higher, but lenders generally offer a lower borrowing cost in exchange for the faster payoff. Over the life of the loan, the interest savings can run into the tens of thousands of dollars.
Adjustable-Rate Mortgages and Government Loans
An ARM gives you a fixed introductory period - often five or seven years - before the cost adjusts annually based on market conditions. That introductory cost is usually lower than a 30-year fixed. Buyers who plan to sell or refinance before the intro period ends sometimes use ARMs to save cash upfront.
For specific buyer profiles, government-backed programs like FHA, VA, and USDA loans offer alternative paths with different down payment requirements and pricing structures right here in Taylor County.
How to Get the Best Mortgage Rate as a Buyer
Lenders reserve their best pricing for borrowers who pose the least risk. You can't control the bond market, but you can control the financial profile you walk in with.
Even small improvements before you apply can show up in your Loan Estimate. Getting your house in order early - before you're actively shopping - gives you leverage when it's time to compare offers.
The Impact of Your Credit Score and Down Payment
Your credit score is the single largest factor in the pricing tier a lender assigns you. A strong history of reliable payments earns you a lower borrowing cost - that's the simple version.
A larger down payment reinforces the same logic. It creates immediate equity and reduces the lender's risk. Borrowers putting down 20% or more typically see better pricing than those using minimum down payment programs.
Shopping Around and Locking Your Rate
Apply with at least two or three lenders and compare their Loan Estimates side by side. Different institutions carry different profit margins and risk appetites, so you'll get different pricing for the exact same Abilene home. That gap is real money.
Once you've chosen an offer, request a rate lock. It protects you from daily market swings for a set period - usually 30 to 60 days - so your budget stays intact while you work toward closing.
Finding the Right Mortgage Lender in Taylor County
A good lender does a lot more than quote a number. They manage deadlines, communicate with the seller's agent, and make sure your closing happens on time. Who you choose affects the whole transaction, not just the rate on page one.
Buyers in Abilene can choose from traditional banks, local credit unions, direct lenders, and mortgage brokers. Each operates differently, and the right fit depends on your situation and how you want to communicate through the process.
Local Lenders vs. National Call Centers
A local Abilene lender knows Taylor County property taxes, the local appraiser pool, and regional insurance requirements. They also have a reputation to maintain in this market, which tends to produce better communication when things get complicated.
National call-center lenders may advertise low upfront numbers, but they often work across multiple time zones with disconnected processing teams. In a market where homes sell in roughly 20 days, a delayed pre-approval or a missed closing deadline doesn't just cause stress - it can cost you the house.
Questions to Ask Before Choosing a Lender
Ask any loan officer you're considering about their average closing timeline and whether underwriting is handled in-house. In-house underwriting typically means faster approvals and fewer last-minute surprises right before closing.
Ask how they communicate outside of standard business hours. Real estate doesn't stop on weekends, and if you want to submit an offer on a Saturday, you need a lender who can update your pre-approval letter that afternoon.
What Rate Trends Mean If You Are Selling
Financing costs control how many buyers can afford your home at a given price point. When borrowing costs drop, more buyers qualify and competition for available listings increases. When costs rise, purchasing power shrinks and the pool of qualified offers gets thinner.
Getting ahead of that dynamic helps you set realistic expectations before you list.
How Rates Shape Buyer Demand Locally
Abilene currently sits at about 1.6 months of housing supply - that still favors sellers. But buyers are working within hard payment limits. If borrowing costs trend upward while your home is listed, some buyers will pause or shift their search to lower price brackets. Watching that trend helps you understand why foot traffic and offer volume look the way they do on any given week.
Pricing and Timing Your Listing
Recent comparable sales should drive your pricing, but current financing conditions affect how aggressively you can position the home. A well-priced listing in a high-cost borrowing environment will still attract serious buyers - it just needs to be priced honestly.
A local agent can help you read market feedback in real time and adjust your approach if buyer demand shifts while you're on the market.
Mortgage Rate FAQs
What are mortgage rates today in Abilene, TX?
Mortgage rates change daily and vary based on your specific financial profile. To get today's exact rate, you need to request a personalized quote or Loan Estimate directly from a lender. Publicly advertised rates rarely reflect what an individual buyer will pay.
How much does a 1% difference in mortgage rate cost me when buying a home in Abilene?
It adds up fast. On a $292,000 median-priced Abilene home with a 20% down payment, a 1% rate increase adds roughly $150 to $200 to your monthly principal and interest payment. Over the life of a 30-year loan, that equals tens of thousands of dollars.
How do I get the best mortgage rate as a buyer in Abilene?
Improve your credit score and save for a larger down payment - those two moves have the most direct impact on the pricing tier a lender offers you. Apply with multiple lenders so you can compare Loan Estimates side by side before you commit.
Should I wait for rates to drop before buying a home in Abilene?
That depends on your timeline and budget. Waiting for lower borrowing costs can backfire if local prices keep rising. Abilene homes are currently selling with a median of 20 days on the market, so delaying a purchase means taking on the risk of higher home prices later.
How do I choose a mortgage lender in Abilene, TX?
Look for a local lender who understands Taylor County taxes and has a track record of closing on time. Ask about communication outside of business hours and whether their underwriting is handled in-house - both tell you a lot about how the process will go.
What credit score do I need to get a good mortgage rate in Abilene?
Lenders generally offer their best pricing to borrowers with a credit score of 740 or higher. You can qualify for certain government-backed loans with much lower scores, but a higher score always translates to a lower borrowing cost.
How do current mortgage rate trends affect me if I am selling my house in Abilene?
When borrowing costs rise, buyers lose purchasing power - fewer showings, fewer offers. When costs drop, demand picks up. In Abilene's tight 1.6-month inventory market, that shift can happen quickly in either direction.
Thinking of Buying or Selling in Abilene? Get Local Guidance
Whether you're buying your first home or pricing a listing, the Abilene market rewards preparation and clear communication. Having the right team in place - a local agent, a lender who knows Taylor County - makes a real difference in how the transaction unfolds.
Reach out to talk through your timeline and get introductions to lenders who work in this market every day.
Amber Kimmel
| Kimmel Collective Real Estate Team | Keller Williams Realty
or another way